If the shop pays MDR, do you still pay? Surcharge vs a higher sticker price
UPI does not add a fee line on your debit. A shop can still change the listed price. Here is what the gazette actually stops, what officials said they will watch from 15 October 2026, and when there is ₹0 MDR to "pass on".
The short answer
On the UPI debit, you still pay the listed bill, not the bill plus a UPI processing line. Banks and apps are not supposed to add a checkout surcharge for the person paying.
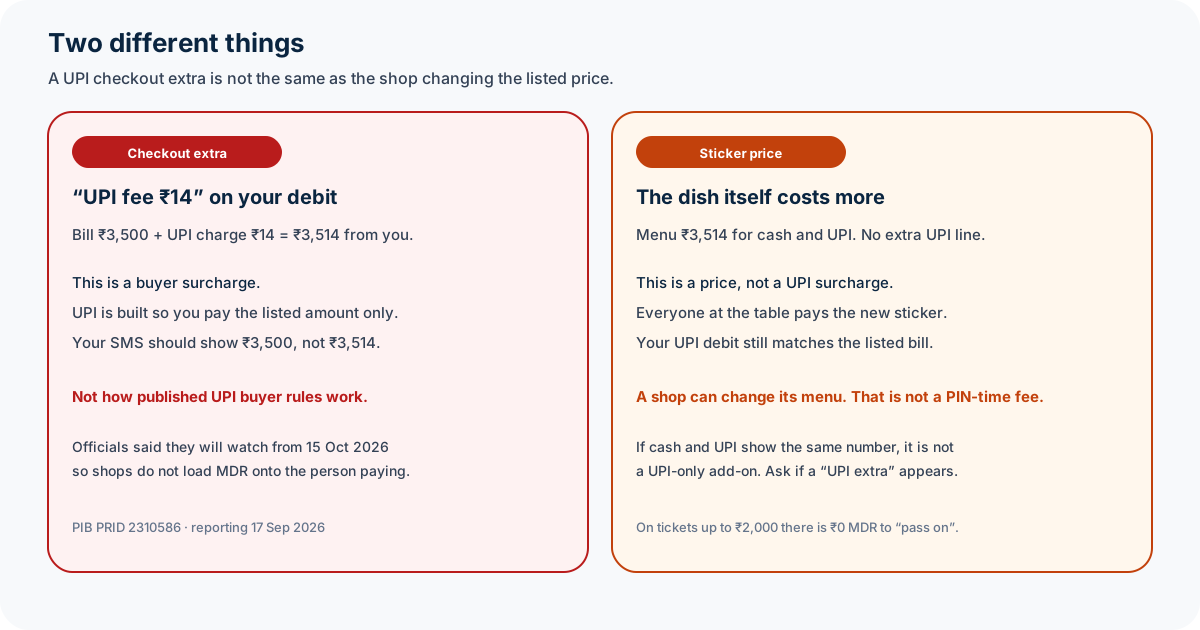
That is not the same as "the shop will never change its prices." A restaurant can reprint the menu. A jeweller can raise the ticket. If cash customers pay the new sticker too, that is a price, not a UPI fee printed at PIN time.
The clear split:
- Prohibited or monitored: a UPI-only extra: "Bill ₹3,500 + UPI ₹14." Your SMS would show more than the listed amount.
- Possible in retail trade: a higher list price: the thali or the ring costs more for everyone. Your UPI debit still matches that new list.
- Often no fee to pass on: tickets up to ₹2,000, friend-to-friend transfers, and small P2PM QR shops in the exempt class have ₹0 MDR. There is no 0.40% fee in the back office to add to consumer prices.
Officials told reporters on 17 September 2026 that from 15 October they will watch daily so banks and aggregators do not pass the new merchant fee on to buyers, and they dismissed rumours of a GST add-on for the person paying. That is news about monitoring, not a promise that every sticker in India stays frozen.
What the gazette actually does
The Ministry of Finance note (PIB PRID 2310586, 15 September 2026) keeps peer-to-peer free and keeps most shop tickets free. Shop MDR on specified person-to-merchant payments above ₹2,000 is the new piece. NPCI FAQ coverage and later reporting say that shop fee applies from 15 October 2026.
| What happens | Who is billed | From 15 Oct 2026 |
|---|---|---|
| Friend / family UPI (P2P) | Nobody | ₹0 both sides, any amount |
| Shop ticket up to ₹2,000 | Nobody | ₹0 MDR (about 96% of shop tickets, per government volume figures in the same framework) |
| Standard shop above ₹2,000 | The shop's bank, from the shop | 0.40%, capped at ₹300 from ₹75,000 |
| Rail, fuel, telecom, insurance, utilities, school fees above ₹2,000 | The merchant | Flat ₹5 |
| Mutual funds / broking | The merchant | 0.02%, cap ₹300 |
| Small P2PM QR into own account, up to ₹1 lakh a month | Nobody | ₹0, per September 2026 FAQ coverage |
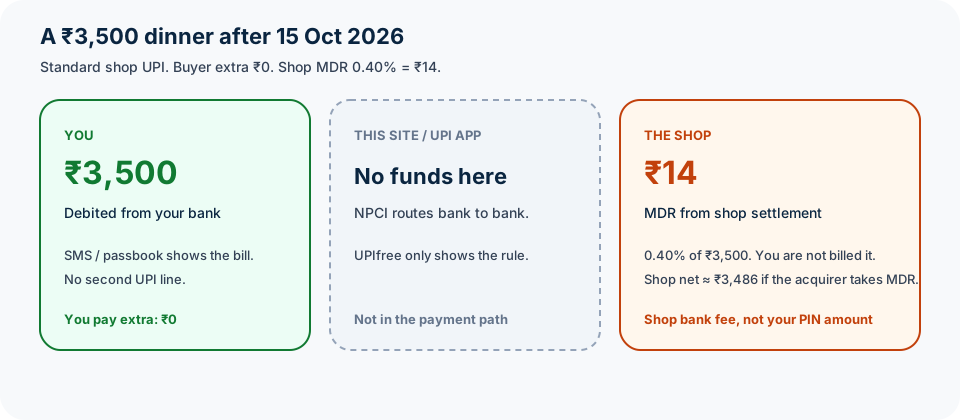
You still PIN the listed amount. The ₹14 on a ₹3,500 dinner is not added to your debit. It is taken, if at all, from what the shop receives.
Use the fee calculator with ₹3,500 to see that split on one screen.
Your bank SMS versus the shop's settlement
Think of two ledgers, not one.
- Your ledger: ₹3,500 leaves your account. That is the consumer-free rule.
- The shop's ledger: the acquiring bank may keep ₹14 (0.40% × ₹3,500) and credit about ₹3,486. That is MDR.
If a waiter writes "UPI extra ₹14" only for people who scan, that is a surcharge on the person paying. If the printed menu already says ₹3,514 for cash and UPI, that is a menu price change.
A payment aggregator can still add rental, setup, or a blended rate on top of gazette MDR. That contract is between the shop and the aggregator. It is not a line on your UPI SMS.
"Then they will just raise the price": analysis of price adjustments
Economics is blunt: a cost on the seller can show up in the sticker, the same way rent and oil do. Nobody needs a gazette to know that.
What the UPI rules change is how it can show up:
It is not a PIN-time UPI tax. You should not see a second debit or a "convenience fee" that only UPI users pay. If you do, that is the behavior officials announced they will monitor from 15 October 2026.
A general price adjustment is different. If the shop raises the listed price for cash, card, and UPI together, every customer pays the new sticker. That is not "UPI charged you." It is the shop resetting its baseline price. Public circulars do not freeze retail prices.
Competition remains relevant. If a competing kirana sells the same goods at the earlier price, adding ₹14 to a ₹3,500 bill is a business choice, not an automatic requirement. On small tickets the MDR is already ₹0, so claims of passing on fees are unfounded.
The cap limits high-ticket deductions. 0.40% of ₹1,25,000 would be ₹500. The published statutory cap is ₹300. Even if a shop attempts to recover acquiring costs ticket by ticket, the gazette sets a ceiling on that recovery for high-value UPI.
When there is no MDR to bake in
If the fee is already ₹0, claims that "we have to pass UPI charges to you" have no regulatory basis.
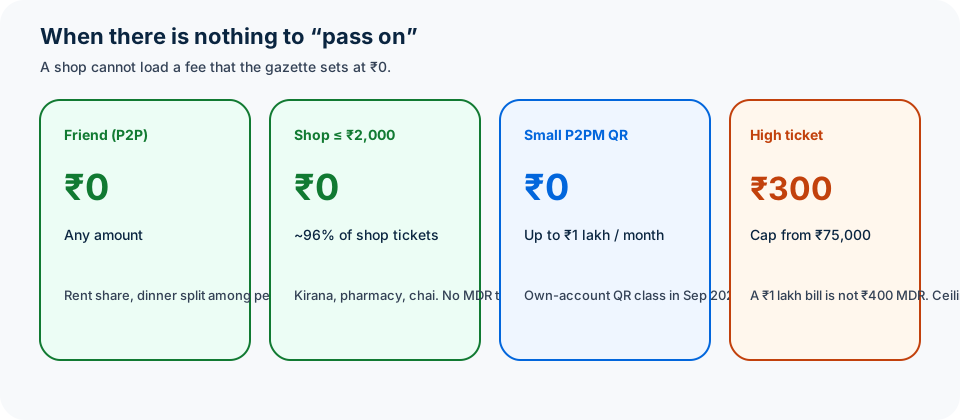
- Kirana ₹1,850: both sides ₹0. There is no 0.40% hiding in the dal.
- Paying a friend ₹5,000 rent share: P2P, ₹0. Do not treat a shop QR as a friend transfer to dodge MDR; that is not what the splitter is for.
- Street QR in the small P2PM class (up to ₹1 lakh a month into the shop's personal account): September 2026 coverage describes ₹0 MDR on every ticket. The shop must be classified under this category by its acquiring bank.
- ₹1 lakh jewellery on UPI: shop MDR ₹300, not ₹400. Buyer extra still ₹0.
Photograph a real slip on the bill reader if you want that split named on the page. Confirm the printed total and your bank SMS; OCR can misread.
What to check at the counter
- Listed amount versus UPI screen versus SMS: All three should match. If UPI shows more than the printed bill, you are looking at a surcharge, not price inflation.
- Cash versus UPI on the same item: If cash is cheaper only because the seller added a "UPI charge", that is non-compliant behavior. If both have the same new price, that is a baseline price change.
- Ticket size: Under ₹2,000, ask what fee they think they are recovering. The published MDR is ₹0.
- High-ticket ceiling: From ₹75,000 the merchant UPI fee stops at ₹300. A "2% UPI extra" on a large bill exceeds the gazette rate.
- GST rumour: 17 September 2026 reporting: officials dismissed GST on top for the person paying. MDR is not GST.
Compare rails on the method finder if the shop pushes a card. Cards often carry a different acquiring rate; that is a separate contract.
Shopkeepers can model turnover on the merchant MDR calculator instead of guessing a round number to add at the till.
What this article is not
It is not legal advice, not a price freeze, and not a claim that no shop will ever raise a sticker. It is a reading of who is billed on the UPI rail (you: listed amount; shop: MDR if any) plus what reporters were told about monitoring in mid-September 2026.
If a later gazette, NPCI FAQ, or court order changes the fee bands, check the rules directory and latest updates, not unverified messages.
Share this article
Help friends, merchants, and colleagues stay informed with verified regulatory facts.
Official Government & Regulatory Citations
- Ministry of Finance PIB PRID 2310586Verify Primary Document
- Mint: Centre to monitor MDR daily from 15 October 2026Verify Primary Document
- India Today: officials dismiss GST-on-UPI rumour for the person payingVerify Primary Document
- NPCI UPI circular indexVerify Primary Document
Put this guide into practice with our 100% free, client-side calculation engines:
UPI Fee Calculator
Instant consumer ₹0 fee check vs shopkeeper MDR across transaction amounts.
Merchant MDR Calculator
Model monthly shop turnover, statutory ₹300 cap savings & yearly retained profit.
Bill reader
Photograph a slip. See buyer extra ₹0 versus shop MDR on the printed total.
Payment Method Finder
Compare UPI, RuPay credit cards, debit cards, and net banking for lowest fees.